


United Asset October Market Update
The S&P 500 continued higher in the 3rd quarter, as highlighted by the 2% return in Exhibit 1 of our quarterly letter, with year-to-date gains nearing 13%. For many, a stock market hovering near all-time highs has been puzzling given concerns about the sustainability of AI-driven growth, weak consumer sentiment from rising mortgage rates and gas prices, geopolitical tensions in Iran and Ukraine, and the uncertainty surrounding the upcoming midterm elections. Beneath the surface, however, we do not view the market as complacent, with negative 3rd quarter returns for the average stock and major bond indices reflecting such concerns. To that end, Exhibit 2 shows most stocks have not participated this year. We also see a year-to-date decline in the multiple investors are willing to pay for market earnings, reflecting risks they see.
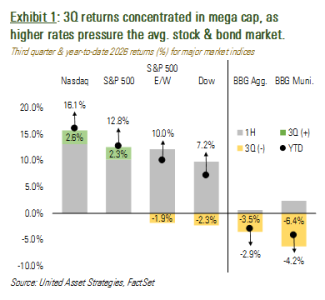
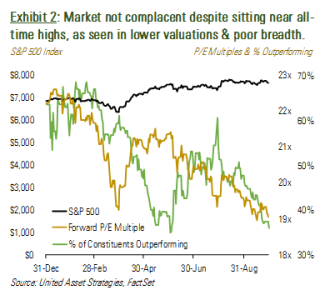
Higher stock and lower bond markets were a result of the macro backdrop. While much attention has been on AI, strength extends beyond it, with consumer spending resilient to higher mortgage rates and gas prices owing to a healthy job market and growing household wealth. Further, strong earnings have offset lower multiples to leave the stock market near all-time highs. And while much of that outsized earnings growth is AI-driven, growth outside the AI complex has also accelerated above historical levels, an indication of a supportive macro backdrop. The disconnect between narrow stock gains and broad earnings strength is notable, however, with reversion toward fundamentals a potential tailwind to our more diversified portfolios. Looking ahead, we acknowledge the policy uncertainty around the midterms but note seasonal strength in the months after as a reason to stay invested.
We point to historical links between the economy and Treasury yields, with accelerating GDP growth contributing to higher rates and lower bond prices. Looking ahead, bonds offer an attractive risk-reward, with yields providing a healthy return above inflation and a cushion against adverse rate changes. From a planning standpoint, balancing debt repayments and liquidity is key to financial flexibility in a higher-rate world. Contact your advisor to discuss.
For more details, find supporting comments & analysis in the full letter here.
________________________________________________
Respectfully submitted by the Professional Staff at United Asset Strategies.
Watch United's Latest Market Insights
Download the full letter here.